Thursday, December 23, 2010

Trends in Algerian Petroleum Production and Consumption

As I discussed in Where in the world does the USA import its oil from? Algeria is number seven on the list of largest petroleum provider to the USA in 2009 based on data from U.S. Total Crude Oil and Products Imports (“Total Imports”). 


Algeria has long been an important supplier to the USA.  For instance, according to data in “Total Imports,” at least since 1975, Algeria has been usually among the top 10 of total petroleum importers to the USA.

According to the EIA’s country analysis brief for Algeria,  the State-owned entity, Sonatrach, controls the oil and natural gas sectors in Algeria, and foreign companies have to enter into partnership agreements with Sonatrach to develop Algeria's oil fields.  The EIA country analysis brief indicates that Algeria’s plan is to maintain crude oil production capacity at about its current level, and points hopefully to Sonatrach’s announcement of the discovery of 16 oil fields since the beginning of 2009 as a sign that this will help replace declines in older fields. 

However, also in 2009 we have Algeria’s Oil Minister announcing the plan to go look for oil and gas in shale and compact formations “to ensure a safe and durable supply of hydrocarbons and petrochemical products to our traditional partners in Europe, Asia and North America.”  (from: Algeria Looking for Shale Gas Deposits, Study Nuclear Power, Minister Says)

To me, this looks like a sign that conventional oil is at or near peak and that now the less attractive sources such a shale oil, requiring substantial foreign investments, is what will be in store for Algeria’s future production. 

According to the EIA country analysis brief, Algeria’s exports are split between about one-third going to North America (the USA and Canada) and two-thirds going to QECD countries like France, Germany, Italy, UK, Japan and South Korea: 

The USA was the biggest single country importer, taking about 27% of Algerian net exports in 2009.

The EIA's Algeria energy profile and “Total Imports” indicates that Algeria’s exports to the USA have trended upwards since at least the mid 90s:


The upward trend, however, is not very strong (linear regression r2 = 0.5).  Therefore for the export analysis to follow, I have assumed that the percentage of Algeria’s exports to the USA will continue at its past 5-year average of 30.5±4 percent.   

Non-linear least squares (NLLS) analysis of total petroleum production
Figure 1 shows total petroleum production for 1965-2009 as reported in the BP statistical review.
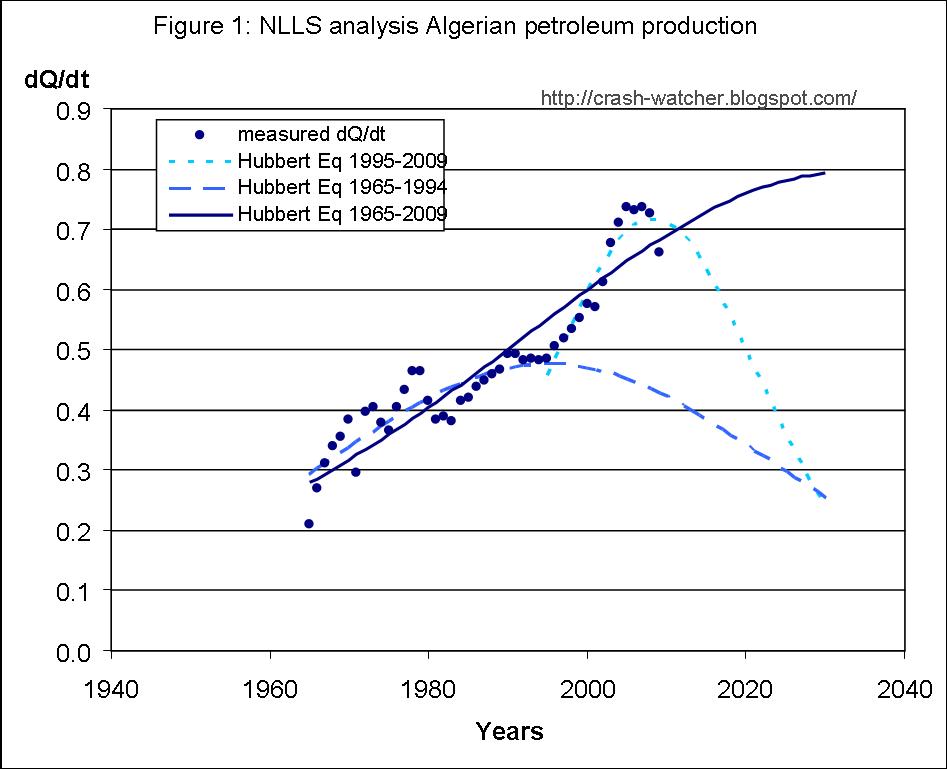


After a gradual increase in the production rate through the 1970s and 80s, production peaked in the early 90s and then took off in the late 90s until about 2004, where production plateaued for about four years and then declined in 2009.  The EIA might want to write-off that decline in 2009 to OPEC quota restrictions, but that would not explain why there was a plateau in production from 2004 to 2008 when world oil demand was high and prices were rising.   Again, to me this looks like a sign of a production peak.

Figure 1 shows the best fit of the Hubbert equation to the entire data set (solid line best fit parameters: “a” = 0.0326; Qo = 9.33; Q∞ = 97.51).   This didn't look like a very good fit to the data as a whole, and so I tried two more Hubbert equation fits to two different smaller time segments: 1965-1994 (long dashed line, best fit parameters “a” = 0.04790; Qo = 7.44; Q∞ = 39.83) and 1995-2009 (short dashed line, best fit parameters “a” = 0.105; Qo = 9.33; Q∞ = 27.24).  As suggested by the difference in value of the rate constant "a" for these two periods, there was a more than a doubling in the production rate from the 1965-1994 period to the 1995-2009 period.

I also tried a fit using my modified Hubbert equation 9 to the 1995-2009 time span,  in which parameters “a” Qo and Q∞ were fixed to the best fit parameters for the 1965-1994 time span, and one or both of fca or fcq were varied. 

Figure 2 shows the best fit for the case where fca was allowed to vary and fcq was fixed equal to 1:


The best fit value for fca was 1.043 (solid green line).  Allowing only fcq to vary gave a poorer fit, and allowing both fca and fcq to vary did not result in a significantly better fit (F-test, p>.1).  This suggests that the behavior of Algerian production since 1995 is most consistent with an about 4.3 percent per year increase in the production rate with no increase in Q∞.  That is, it looks like Algeria has just been pumping the oil that it has at an increasing rate, without expanding its reserves. 

The best fit using modified equation 9, however, did not give a better fit than the Hubbert equation fit to the 1995-2009 time period so I will stick with the Hubbert equation fit for the further analysis to predict future exports.  I note however, that as illustrated in Fig. 2, these two fits for the 1995-2009 period (solid green and short dashes) are nearly identical, so it would not have mattered too much which one I had chosen to use for my export analysis. 

Non-linear least squares (NLLS) analysis of total petroleum consumption
Figure 3 shows the Algerian consumption data from 1965 to 2009 as reported in the BP statistical review:


The first thing to note about this plot is that the vertical scale here is about an order-of-magnitude lower than the scales shown in Figures 1 and 2—that is, Algeria doesn’t use much of the petroleum it produces.  However, after a plateau in the mid 90s and then down turn in the late 90s, consumption took off in strong upswing through the 2000s. 

That upward swing in the last decade causes the Hubbert equation to the full data range (solid line in Figure 3) to be quite a poor fit.  The Hubbert equation fit to the smaller period from 1965-1996 (long dashes best fit parameters: “a” = 0.130; Qo = 0.067; Q∞ = 2.34) was much better, however. 

To better model the consumption trend from 1997 to 2009, and beyond, I again turned to my modified Hubbert equation 9, setting “a” Qo and Q∞ to the best fit parameters for the 1965-1996 time span and allowing one or both of fca or fcq to vary.   


Figure 4 shows the fit results for the case where fcq equal to 1.04 and fca fixed equal to 1.  The overall best fit to the 1965-2009 time span using the Hubbert best fit parameters for 1965-1996 plus the modified best fit for 1997-2009 tme span (sum of  rss = 0.0007) was significantly better (F-test p<0.0001) than the fit obtained using the Hubbert equation for the full 1965-2009 time span (rss = 0.0117).  Allowing fca to vary and fixing fcq=1, did not result in a better fit, and varying both fca and fcq did not result in a significantly better fit (F-test, p>.1).

The value of fcq equal to 1.04 is consistent with the Q∞ for consumption increasing at a yearly rate of 4%/yr for the period 1997-2009.  I extended this trend out to 2030 in Figure 4 to illustrate that, although domestic consumption has been fairly low in the past, it will start to more substantially eat into production in the future if the consumption trend continues. 

Predicting future trends in Algerian petroleum exports
Figure 5 shows the production and consumption data from 1965-2009 and the best fits obtained using the modified Hubbert equation analysis of the 1997-2009 time period of consumption data and the Hubbert equation fit to the 1995-2009 period of production data.


The predicted export curve (solid green line) is calculated based on the difference between the production and the consumption curves shown in the figure. 

Additionally, I show the estimated “measured” export data from 1997-2009 (i.e., the BP statistical review reported production rate minus the reported consumption rate). 

The predicted production and consumption trends suggests that Algeria’s net exports would end in 2029, due to combination of declining production and increasing domestic consumption.

Impact on USA
Figure 6 reproduces the USA production and consumption trends, plus the previously discussed top-six petroleum exporters to the USA measured and predicted future exports as presented in the previous article, Trends in Russian Petroleum Production and Consumption.


Based on the predicted export trend, Algeria’s exports to the USA by 2015 is predicted to equal about 0.151 bbs/yr and only 0.102 bbs/yr by 2020.  That is 91% and 62%, respectively, of Algeria’s estimated exports to the USA in 2009 (0.162 bbs/yr).  If the trends continue, somewhat similar to Nigeria, Algeria will continue to be an increasingly important exporter to the USA in the 2010s, overtaking Mexico by 2012 and Russia by 2018 in terms of its exports to the USA, before dropping to very low levels of exports by the mid 2020s, and none by 2029.

Algeria adds another small sliver of petroleum to the USA's total import sources, at least until 2029.

Saturday, December 18, 2010

Where in the world does the USA import its oil from?

This article is a follow-up to address a question I posed at the end of the article, Trends in Nigerian Petroleum Production and Consumption.

After considering the USA’s petroleum imports from its top five source countries, I pondered the question: where did the additional ~1-2 bbs/yr petroleum come from for the years 2004-2009 to account for the discrepancy between the USA’s consumption and the USA’s domestic production, plus the imports from its top 5 importers? 

I can now re-phase this question, “from the top 6 importers,” because after considering number six, Russia (see Fig 4 also reproduced below), there is still an about 1.5 bbs/yr discrepancy.


Even after considering the top six petroleum importers and domestic production, I still can not account for about 1.5 bbs/yr worth of petroleum imports into the USA especially in those peak consumption years around 2005-06. 

Where did that petroleum come from?

Since posing this question, I have found a source of information that helps shed some light on where in the world the USA imports its oil from.  The EIA has published a spread sheet entitled, U.S. Total Crude Oil and Products Imports (hereinafter, “Total Imports”). 


“Total Imports” is a massive spreadsheet that presents average US imports (in units of 1000s of barrels per day) of Crude Oil plus Petroleum Products, for the years 1973 to 2009 from about 30 to 90 difference source countries depending on the year being considered.  

It is just what I needed to answer my question.


Top Suppliers of Petroleum Imports to the USA in 2009

One thing I would like to correct, from the start, is a mistaken assumption that I had made about Fig. 5.4 of the Annual Energy Review for 2009 (and its associated Table 5.4).  Here it is one more time:


My mistake was to assume that the EIA was actually showing the top nine countries in their order of importance.  I should have been made more suspicious by the title, “Selected Countries.” 


According to the data presented in “Total Imports,” however, the top 10 countries exporting petroleum to the USA are presented below.


Notice that I have added to Venezuela, the separate entry in “Total Imports,” of imports for the US Virgin Islands (VI).  As already discussed in Trends in Venezuelan Petroleum Production and Consumption, the VI imports substantially all of its oil from Venezuela, and then passes the oil and petroleum products on to the USA.  This would actually put Venezuela + VI ahead of Mexico as the second largest petroleum exporter to the USA in 2009.


I find it curious that Fig. 5.4 of the Annual Energy Review excludes Algeria and Angola but rather includes the UK.  Why would the EIA choose to not feature the imports from Algeria and Angola, which together account for about 8 percent of the total exports, and instead, show imports from the UK, which provided only about 2 percent?  According to “Total Imports,” the UK is only the twelfth largest supplier, behind Columbia at 2.4 percent.   Actually, thirteenth, if I were to consider VI separately (VI would be tied with Columbia at 2.4%). 


Maybe the EIA’s goal was to portray the UK as still an important supplier, or, to suggest (by omitting Algeria and Angola) that petroleum from Iraq or Brazil are relatively more important than they actually are. 


The values in parenthesis above the bars in Figure 1 show each country’s the exports to the USA as reported in “Total Imports,” after conversion of 1000s of barrels per day into units of bbs/yr.  The sum of the imports from these ten countries (or 11, if you wanted to count VI separately) equals about 78% of the USA’s imports for 2009 or about 3.3 bbs/yr.  Added to my USA production for 2009 (2.6 bbs/yr; from the solid blue data point at 2009 in Fig. 4, from Trends in Russian Petroleum Production and Consumption, reproduced above) gives about 5.9 bbs/yr or about 80 percent of my estimate of USA’s consumption for 2009 (7.4 bbs/yr; from the solid red line in Fig. 4 above), or, about 87 percent of the reported consumption (6.8 bbs/yr; from the red data point in Fig. 4 for 2009).

To account for a larger portion of US imports, I considered all the countries in “Total Imports,” that contributed at least about 1 percent to the total US imports for 2009.  I ended up with sixteen countries (Norway contributed only 0.92 percent, but I accepted this as about 1 percent) shown in Figure 2 below:


The sum of the imports from these sixteen countries equals about 88% of the USA’s imports for 2009,  about 3.7 bbs/yr.  Added to USA estimated production for 2009 (2.6 bbs/yr) gives about 6.3 bbs/yr or about 85 percent of my estimated consumption for 2009 (7.4 bbs/yr), or, about 93 percent of the reported consumption (6.8 bbs/yr).

To account for the remaining 12% of the USA’s imports, I would have to “scrape lower into the barrel” of importers so to speak.  According to “Total Imports,” there were 82 countries that made a "non-zero" contribution to the USA’s imports in 2009, which for the purposes of the spread sheet was at least 1000 barrels/day. 

The sum from all 82 countries equaled 4.3 bbl/yr which added to US production of 2.6 bbl/yr gives 6.9 bbl/yr which is just slightly higher than the reported consumption of 6.8 bbl/yr.  Perhaps the discrepancy is a rounding error, or, because the 6.8 bbl/yr value is from the BP Statistical Review, while the 6.9 bbl/yr is from the EIA’s “Total Imports.” 

Thirty-three countries each contributed from 0.1 to 0.9 percent of USA’s total imports.  These countries, 17 through 50, in total contributed about 11 percent of the USA's imports.  The top five among this group are Equatorial Guinea (0.76%); Trinidad & Tobago (0.72%); Libya (0.68%); Azerbaijan (0.64%) and Chad (0.59%).  The remaining thirty-one countries (e.g., countries like Japan, Qatar, China, Egypt, Malaysia etc...) each contributed less than 0.1 percent of USA's imports, and in total contributed about 1% of the USA's imports.

Historic Petroleum Imports to the USA from the Top Importers of 2009
Figure 3 shows how well these top 10, or top 16, import source countries account for USA’s imports in the past.  Figure 3 is a variation on Figure 4, which still shows production and consumption data from the USA and my best fits, but replaces the export data derived from BP statistical review, and my NLLS analysis of this data, with the import data presented in “Total Imports.” 


Also shown is the additional contribution from the remaining countries 17-81 (with VI’s exports combined with Venezuelan).  

Figure 4 casts the data shown in Figure 3 in percentage terms.  That is, for each year, USA reported production plus the imports from the top 10 importers for 2009 (i.e., the countries shown in Fig.2), the top 16 importer for 2009 (i.e., the countries shown in Fig. 3), and all of the importers (i.e. at least 1000 b/d) for the year in question are shown as a percentage relative to reported consumption for the year in question.


For the entire 36 year period, USA production plus the top 10 importer from 2009, on average, accounted for 85.8±2.5 percent of USA consumption.  USA production plus the top 16 importers from 2009, on average accounted 90.3± 3.3 percent of USA consumption.  Considering only the 28 year time span from 1981 on, to exclude the dip centered at 1978, did not substantially change these averages (86.4±2.2 and 91.8±1.1, respectively).

That dip centered at 1978 is due the fact that, back then, there were significant sources of imports from a number countries that are not among the top 10 or top 16 providers in 2009, as illustrated in Figure 5 below:


Figure 5 considers all of the countries in 1978 that contributed at least about 1% to the USA’s total imports in that year.  As before, I combined the contributions from Venezuela and VI (8% and 5.3% respectively).  I might well have also added to Venezuela the petroleum from other Caribbean countries like Netherland Antilles, Bahamas and Puerto Rico (Trinidad & Tobago produces much of its own oil) but I couldn’t verify that, like VI, they were importing from Venezuela and then re-exporting to the USA.  

USA imports from Iran ended in 1979 after the Iranian-hostage taking incident and imports from Libya ended in 1982 after the USA declared an import/export ban.  As indicated above, since about 2005, after then ban was lifted, Libya has been making a come back as an important import source.  Substantial imports from Indonesia continued for another decade, but by the mid-1990s was less than 1%. and continued declining  Petroleum from the UAE dipped below 1% after 1980. 

Using the top 10 importers to predict USA consumption
Not withstanding the discrepancy in late 1970s, the sum of USA production plus the imports from the top 10 importers for 2009 accounts for a fairly constant 86 percent of USA consumption for a plus-three decade period of time.  This suggests that these data would be useful for predicting the USA’s consumption going forward.

For instance, consider Figure 6 below, which presents the same USA production and consumption data as shown in Figure 3:
Additionally, I have shown the sum of USA production plus the imports from the top 10 import sources (dashed green line) and this sum divided by 0.86 (solid green).  With the exception of the late 1970s, the solid green line tracks the reported USA consumption data pretty well.

This analysis gives me some assurance that by just considering and predicting USA production and imports from the top 10 importers, I can make a reasonably accurate prediction of USA consumption going forward. 

Now, I just need to finish the analysis for the remaining top 10: Algeria, Angola, Iraq and Brazil!

Next stop...Algeria.